Financial Blog
Employer Stock Concentration Risk: How to Unwind Company Shares Tax-Efficiently
Kris Alban | Oct 05 2026 12:00
Holding a high concentration of employer stock exposes investors to substantial single-company risk, as both primary earned income and net worth become dependent on a single firm's financial trajectory. Financial industry standards typically consider a holding of more than 10% of a portfolio's total value in a single stock to be a concentrated position ( https://www.morningstar.com/personal-finance/are-you-taking-too-much-risk-your-portfolio ).
Unwinding these shares requires balancing market risk against potential capital gains taxes. Below, we examine the mechanics of employer stock concentration risk and explore systematic methodologies for diversification and wealth management.
What Is Employer Stock Concentration Risk?
Employer stock concentration risk occurs when equity compensation - such as Restricted Stock Units (RSUs), Incentive Stock Options (ISOs), Non-Qualified Stock Options (NSOs), or Employee Stock Purchase Plans (ESPPs) - comes to represent a dominant percentage of an investor's overall asset base.
This concentration creates a dual-exposure scenario. If the employer experiences financial distress, the employee faces potential income disruption along with significant portfolio depreciation.
Data on individual stock performance underscores the structural risk of single-stock holdings:
- Historical market analyses show that roughly 66% of individual stocks underperform broad market index benchmarks over their lifetime ( https://assets.jpmprivatebank.com/content/dam/jpm-pb-aem/global/en/documents/eotm/agony-ecstasy-2021.pdf ).
- Approximately 42% of all public stocks experience a negative absolute return over their life cycle, highlighting the volatility inherent in un-diversified positions ( https://assets.jpmprivatebank.com/content/dam/jpm-pb-aem/global/en/documents/eotm/agony-ecstasy-2021.pdf ).
- Historical case studies - such as Enron in 2001 (where 401(k) plans held over 62% company stock), Lehman Brothers in 2008, and Silicon Valley Bank in 2023 - demonstrate how rapid corporate declines can simultaneously impact employment income and accumulated retirement assets ( https://www.hsgac.senate.gov/media/reps/retirement-insecurity-401k-crisis-at-enron/; https://www.library.hbs.edu/special-collections-and-archives/exhibits/lehman/global-impact-of-the-collapse ).
For sustainable long-term wealth management, managing this single-stock exposure is a central priority.
The Tax-Conscious Wealth Management Approach to Unwinding Stock
The challenge in reducing employer stock concentration risk is managing the resulting tax liability. Selling appreciated shares can trigger federal Long-Term Capital Gains taxes of up to 20%, the 3.8% Net Investment Income Tax (NIIT), and applicable state capital gains taxes.
Comprehensive wealth management frameworks utilize structured unwinding strategies to mitigate this drag.
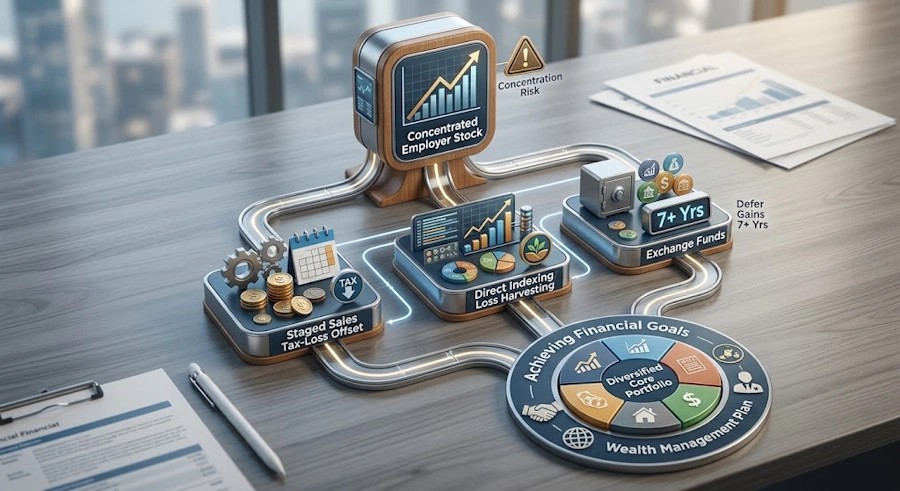
1. Multi-Year Staged Tranche Sales
Rather than liquidating a position in a single tax year, investors can spread sales across multiple calendar years. This approach helps manage exposure to higher tax brackets and aligns capital gain realizations with years of lower income.
2. Direct Indexing and Systematic Loss Harvesting
Direct indexing involves owning the individual underlying equities of an index inside a Separately Managed Account (SMA). By systematically harvesting realized losses within the index tracking account, wealth management strategies can offset capital gains generated from selling concentrated employer stock.
3. Contribution to Exchange Funds
Qualifying accredited investors can contribute concentrated stock into an exchange fund in exchange for a pro-rata share in a diversified pool of private assets. Under internal revenue codes, this contribution generally does not trigger an immediate taxable event, deferring capital gains recognition for the required minimum seven-year holding period.
4. Charitable Transfers via Donor-Advised Funds (DAFs)
Gifting highly appreciated company shares to a Donor-Advised Fund or public charity eliminates the capital gains tax on the contributed shares while providing a fair market value charitable deduction.
Comparing Unwinding Strategies
The following table compares common methods for managing concentrated equity compensation positions:
| Strategy | Primary Mechanism | Tax Impact | Best For |
|
Staged Sales |
Liquidation over multi-year intervals |
Incremental capital gains recognition |
Positions with moderate unrealized gains |
|
Direct Indexing |
Offsetting gains with harvested losses |
Reduced net capital gains exposure |
Active portfolios with ongoing gains |
|
Exchange Funds |
Pooling stock for diversified fund shares |
Deferral of capital gains (7+ years) |
High-net-worth positions with low cost basis |
|
Charitable Gifting |
Direct transfer of appreciated stock |
Avoidance of capital gains tax + deduction |
Individuals with philanthropic goals |
Frequently Asked Questions
What threshold indicates high concentration risk in employer stock?
Financial planning guidelines generally treat any single stock holding that exceeds 10% to 15% of total liquid net worth as a concentrated exposure.
How do Rule 10b5-1 plans help corporate executives manage company stock?
Rule 10b5-1 plans allow corporate insiders to establish predetermined, schedule-based trading plans to sell shares automatically. This helps executives diversify company stock in compliance with insider trading regulations.
What is the tax treatment for vested RSUs versus stock options?
Vested RSUs are taxed as ordinary compensation income based on the fair market value of the shares on the vesting date. Stock options (such as NSOs and ISOs) incur tax upon exercise or sale, with ISOs subject to potential Alternative Minimum Tax (AMT) considerations.
Wealth Management Next Steps
Addressing employer stock concentration risk requires balancing single-company exposure, tax efficiency, and long-term financial goals. A personalized strategy evaluates cost basis, vesting schedules, and overall portfolio structure.
To analyze your equity compensation exposure and evaluate structured unwinding options, consider consulting with a qualified wealth management professional.
About BSG Advisers
At BSG Advisers, we are dedicated to helping individuals, families, and business owners across Apex, Cary, Holly Springs, Raleigh, and throughout Wake County navigate their financial journeys with confidence. We strive for a deeply personalized, client-first approach - combining sophisticated, customized wealth strategies with the local, approachable service you expect from a Triangle-based team. Whether you need comprehensive retirement planning, tax-efficient investment strategies, or proactive business advice, we translate complex financial decisions into a clear, actionable roadmap aligned with your life goals.
Ready to secure your financial future with a trusted local partner? Contact us to schedule a meeting, or call our office to discover how we can help you build, grow, and protect your wealth.